Introduction: Asian stocks headed for worst week since 2020
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
Anthropic’s historic IPO yesterday certainly lived up to the hype, ending the day at a whopping $1.7tn valuation – but it looks like has failed to allay investor concerns around an AI bubble.
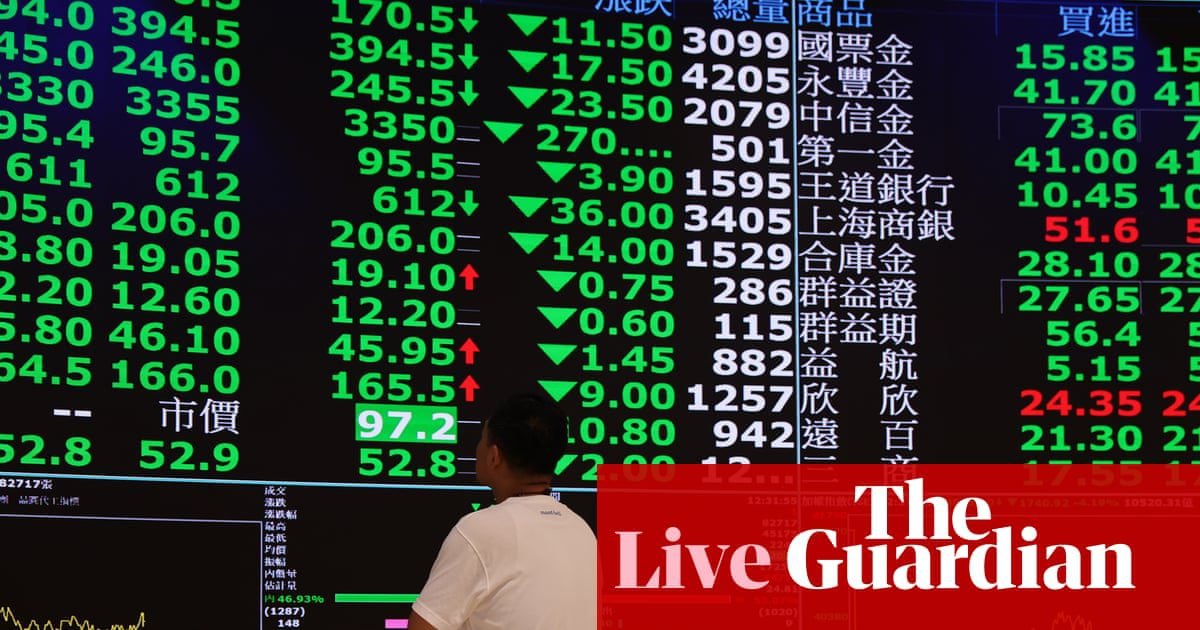
Asian stock markets have sold off overnight, led by falls at big chip companies, and are now on track for their worst week since 2020.
In Taiwan, stocks dropped 6.7% to hit their lowest point since mid-April, deepening its weekly loss to more than 16%, and putting them on track for their worst five-day rout since 1990. TSMC, a leading chip manufacturer and by far the most valuable company in Taiwan’s stock market, fell by about 6%.
South Korean stocks also fell more than 5% to their lowest in more than nine months, with Samsung Electronics and SK Hynix both falling by about 7%. The falls have pushed the MSCI EM Asia equity index down more than 4% to levels last seen in early April – the index has lost nearly 9% this week, and is on track for its worst week since mid-March 2020.
Meanwhile Anthropic itself has fallen by 4.7% in after hours trading to $92.60, below its lowest level yesterday.
Its IPO has failed to ease worries around the AI trade, as investors increasingly question whether companies can deliver the returns necessary to justify the billions of dollars being poured into the AI buildout.
Jim Reid, of Deutsche Bank, notes that Hong Kong’s Hang Seng index is now also approaching bear-market territory as it is down almost 20% from its peak in January.
The CSI 300 (-1.85%), Shanghai Composite (-2.10%), and Australia’s S&P/ASX 200 (-1.58%) are also posting notable declines. The downward momentum is continuing in futures with contracts on the S&P 500 (-0.50%), Nasdaq 100 (-0.98%) and Stoxx (-1.70%) all notably lower with Europe catching down.
The risk-off tone has also weighed on a wide variety of other asset classes, with gold (-2.68%) sliding to a 14-month low of $3,625/oz yesterday and down another -2.2% this morning. Bitcoin (-1.25%) has fallen to its lowest level since early July, and US HY credit spreads (+6bps) reaching their widest level since May at 344bps.
Matters haven’t been helped by the latest geopolitical headlines, which helped push energy prices higher and added to fears about inflationary pressures.
Among others, Axios reported that the White House had asked the Pentagon and intelligence experts for their view on how Iran would respond to the different strike scenarios prepared by the US military. So that echoed the previous evening’s report in the New York Times that President Trump was considering plans for further strikes on Iran.
The agenda
-
7am GMT: ONS public finances, ONS retail sales
-
3pm GMT: University of Michigan’s consumer confidence report for November
-
Today: UK-EU summit – Andy Burnham will meet António Costa, President of the European Council, and Ursula von der Leyen, President of the European Commission, in Brussels on 20 November 2026 for the second UK-EU summit
Key events
Anthropic shares fall 6% in pre-market trading
Anthropic shares are now down 6% in pre-market trading, in a sign that the stock is likely to fall sharply in its second day of trading.
The AI developer closed its first day of trading on the US stock market yesterday about 17% higher than its initial public offering price. At the close, Anthropic shares were trading at just over $97 with a nearly $1.3tn total market capitalisation, $1.75tn fully diluted.
However worries continue to grow about a possible AI bubble in the stock market, with investors questioning whether companies can justify the huge amounts of spending and borrowing to fund the AI build out and astronomical valuations in the sector.
Earlier this month the US midterm election result triggered a tech sell-off amid speculation that a Democrat-controlled Congress could lead to tighter control of AI and datacentre construction.
Meanwhile the resignation of Nvidia CEO Jensen Huang has thrown one of the most valuable companies in the sector into uncertainty as it seeks a new leader.
British retail sales surge as households stockpile emergency supplies
Retail sales in Great Britain surged last month as the public rushed to buy products including tinned food and long-life milk, after the government issued a warning to stock up in case of a disaster.
The ONS has announced this morning that the volume of goods sold jumped 0.7% month-on month in October, defying economists’ consensus expectations of flat sales, as “preppers” took heed of the government’s Be Ready campaign to hold supplies to last 72 hours to survive a potential weather, cyber or other serious emergency.
It is a welcome bounceback for the industry after a poor September, which the ONS has revised down from a 0.4% fall to a 0.6% fall, fuelled in part by poor online sales of autumn and winter clothing because of unseasonably warm weather.
Fitzner said:
Supermarkets have told us that sales of long-life food items such as tinned food and UHT milk were boosted by the government’s ‘Be Ready’ campaign.
European stocks fall as AI sell-off spreads
The AI sell-off is spreading this morning, with the European stock market also opening lower.
The Stoxx Europe 600, which tracks the biggest companies on the content, is down 1% and is on track to end the week down 4.5% – its worst performance since March.
The UK’s blue chip FTSE 100 index is holding up relatively well, down by just 0.3% today – no doubt helped by its lack of big tech companies. The German Dax is down 1.3% and the French Cac 40 is down 0.9%. Chip companies ASML and Infineon Technologies are down by 2.8% and 4.8% respectively as the rout in AI-related stocks continues.
Richard Hunter, head of markets at the broker Interactive Investor, says:
The huge capital investment in the buildout thus far, the possibility of datacentre slowdowns given the recent Democratic sweep and the Nvidia CEO resignation which raises questions around China and US national security all played a part in weakening the AI trade.
There is no doubt that AI is here to stay, and the Nvidia results earlier in the week were initially well received and proof that underlying demand is still far from being satisfied, but the heady stock valuations have led to inevitable doubts on the scale and timing of any ultimate payback.
He notes that in the UK, tech-focused investors and stocks have suffered this morning.
Stocks seen as being more tech-related were in the direct line of fire, with falls of 5% for Polar Capital and 3% for Scottish Mortgage and Computacenter.
A broad markdown elsewhere was enough to overwhelm any attempted offset from some buying in the defensive sectors, although again the overall losses were mild in comparison to the wider global weakness which is threatening to become something of a Santa rout, as opposed to the rally which had been anticipated.
The FTSE 100 has seen its own gains for the year shaved to 4.8%, and the index is now away from the record closing high which it threatened to breach only last week by the same amount.”
Emma Reynolds, chief secretary to the Treasury, is upbeat about the public borrowing figures this morning. She said in a statement:
Fiscal discipline underpins the decisions this government makes everyday. Britain is showing stand-out resilience despite the global impact of the conflict in Iran. We’re building on that.
This year we’ve cut borrowing faster than any other G20 country. Now we’re going to cut waste and bureaucracy by reprioritising spending and making public services more efficient with AI.”
Rob Wood, chief UK economist at the consultancy Pantheon Macroeconomics, notes that while the government will be pleased with the data this morning, “the October budget did little to address the more serious challenges facing the public finances.”
We continue to have doubts about the government’s ability to follow through on its fiscal plans, suggesting upside risks to borrowing in the coming years.
For now, we have to compare October’s data to the [Office for Budget Reponsibility’s] forecasts consistent with the spring statement, as the monthly profiles produced as part of budget 2026 have yet to be released.
But on that basis, government borrowing in the first seven months of the 2026/27 fiscal year is now estimated to have overshot the OBR’s expectations by £3.3bn, down from the £6bn estimated in last month’s figures, which ran to September. [Public sector net borrowing] for October alone overshot the March 2026 forecast by £0.8bn.
We should get the latest profiles from the fiscal watchdog later today, but the OBR raised forecast public sector borrowing in 2026/27 by £17.7bn, of which £6bn had already fallen in the first six months of the fiscal year, meaning the residual would boost borrowing by £2bn if spread evenly over the final half of 2026/27. On that basis, borrowing for October in isolation undershot expectations by around £1.2bn.”
UK government borrowing rises less than forecast
And closer to home this morning: the UK government borrowed less than expected in October despite a rise in debt interest costs, in a boost for chancellor John Healey amid the pressure on Britain’s economy from the Middle East war.
The Office for National Statistics (ONS) said public sector net borrowing – the difference between government spending and income – was £17bn in October, about £800m higher than the same month a year ago. City economists had forecast borrowing would increase to £18bn.
In the financial year so far, public sector net borrowing was £111.3bn, the ONS said – £7.3bn less than in the same period last year.
Grant Fitzner, the ONS chief economist, said:
Borrowing so far this financial year remained lower than in the same period last year with receipts growing faster than spending. Income-related taxes’ receipts grew particularly strongly.
However, monthly borrowing was up on last October, partly down to higher debt interest.”
SoftBank shares suffer worst day in over two years
More pain in the market today – shares in the tech investor SoftBank have suffered their worst day in more than two years amid worries around its aggressive bets on AI.
The Japanese firm is one of the biggest investors in Anthropic’s rival OpenAI, which slashed its fundraising target by $10bn last month in a funding round.
SoftBank shares are down by more than 14% today, putting it on track for its worst day since August 2024.
This week founder Masayoshi Son told a tech conference in Tokyo that he regretted not investing in Anthropic before its IPO.
The Financial Times reported he said:
We did have meetings [about investing in Anthropic]. But by that point, we had already decided to invest in OpenAI, and had already started doing so. So in that sense, there was a reluctance to pursue it further.
This is an example of one of my mistakes.
Yesterday Anthropic became one of the most valuable publicly traded businesses in the world, ending its first day on the US stock market about 17% higher.
Chief executive Dario Amodei said the IPO “puts the company in a stronger financial position, and in doing so only strengthens our resolve to do the right thing.”
Anthropic has seen explosive growth in revenue every year of its existence – sometimes more than 1,000% – according to its investor prospectus, filed at the end of October. The company brought in $16.2bn in the first six months of 2026, up from $4.6bn in revenue for all of 2025.
Introduction: Asian stocks headed for worst week since 2020
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
Anthropic’s historic IPO yesterday certainly lived up to the hype, ending the day at a whopping $1.7tn valuation – but it looks like has failed to allay investor concerns around an AI bubble.
Asian stock markets have sold off overnight, led by falls at big chip companies, and are now on track for their worst week since 2020.
In Taiwan, stocks dropped 6.7% to hit their lowest point since mid-April, deepening its weekly loss to more than 16%, and putting them on track for their worst five-day rout since 1990. TSMC, a leading chip manufacturer and by far the most valuable company in Taiwan’s stock market, fell by about 6%.
South Korean stocks also fell more than 5% to their lowest in more than nine months, with Samsung Electronics and SK Hynix both falling by about 7%. The falls have pushed the MSCI EM Asia equity index down more than 4% to levels last seen in early April – the index has lost nearly 9% this week, and is on track for its worst week since mid-March 2020.
Meanwhile Anthropic itself has fallen by 4.7% in after hours trading to $92.60, below its lowest level yesterday.
Its IPO has failed to ease worries around the AI trade, as investors increasingly question whether companies can deliver the returns necessary to justify the billions of dollars being poured into the AI buildout.
Jim Reid, of Deutsche Bank, notes that Hong Kong’s Hang Seng index is now also approaching bear-market territory as it is down almost 20% from its peak in January.
The CSI 300 (-1.85%), Shanghai Composite (-2.10%), and Australia’s S&P/ASX 200 (-1.58%) are also posting notable declines. The downward momentum is continuing in futures with contracts on the S&P 500 (-0.50%), Nasdaq 100 (-0.98%) and Stoxx (-1.70%) all notably lower with Europe catching down.
The risk-off tone has also weighed on a wide variety of other asset classes, with gold (-2.68%) sliding to a 14-month low of $3,625/oz yesterday and down another -2.2% this morning. Bitcoin (-1.25%) has fallen to its lowest level since early July, and US HY credit spreads (+6bps) reaching their widest level since May at 344bps.
Matters haven’t been helped by the latest geopolitical headlines, which helped push energy prices higher and added to fears about inflationary pressures.
Among others, Axios reported that the White House had asked the Pentagon and intelligence experts for their view on how Iran would respond to the different strike scenarios prepared by the US military. So that echoed the previous evening’s report in the New York Times that President Trump was considering plans for further strikes on Iran.
The agenda
-
7am GMT: ONS public finances, ONS retail sales
-
3pm GMT: University of Michigan’s consumer confidence report for November
-
Today: UK-EU summit – Andy Burnham will meet António Costa, President of the European Council, and Ursula von der Leyen, President of the European Commission, in Brussels on 20 November 2026 for the second UK-EU summit
Source: https://www.theguardian.com/business/live/2026/nov/20/asia-stocks-worst-anthropic-ipo-ai-stock-market-latest-updates-news
About the Author